Tokenized Stocks Are Entering DeFi Collateral, So Routes Need Market-Hour Context
Tokenized stocks are finding a second life as DeFi collateral. Each new venue adds a routing question: which representation, chain and liquidity source can carry a position with clear evidence?
The signal: tokenized stocks are entering a live DeFi market
A recent X search surfaced a clear shift in the tokenized-equity conversation. David Tso highlighted Coinbase tokenized stocks on Base and quoted Token Terminal data showing weekend position increases in the Aave market. The post is here: https://x.com/davidtsocy/status/2109750984331423996.
The observation connects two markets that used to sit apart. A stock token can represent exposure to an offchain share, then become collateral inside an onchain lending market. Aave's September 25 launch note describes seven Coinbase Tokenized Stocks available as collateral on Aave V4 on Base, with USDC as the borrowable asset: https://aave.com/blog/coinbase-tokenized-stocks.
Coinbase describes the same asset family as B20 tokens on Base that can be held in self-custody and used across the Base DeFi ecosystem: https://www.coinbase.com/en-ca/tokenize. The product surface now includes issuance, custody, lending and liquidity. Every added surface creates more state for a router to carry.
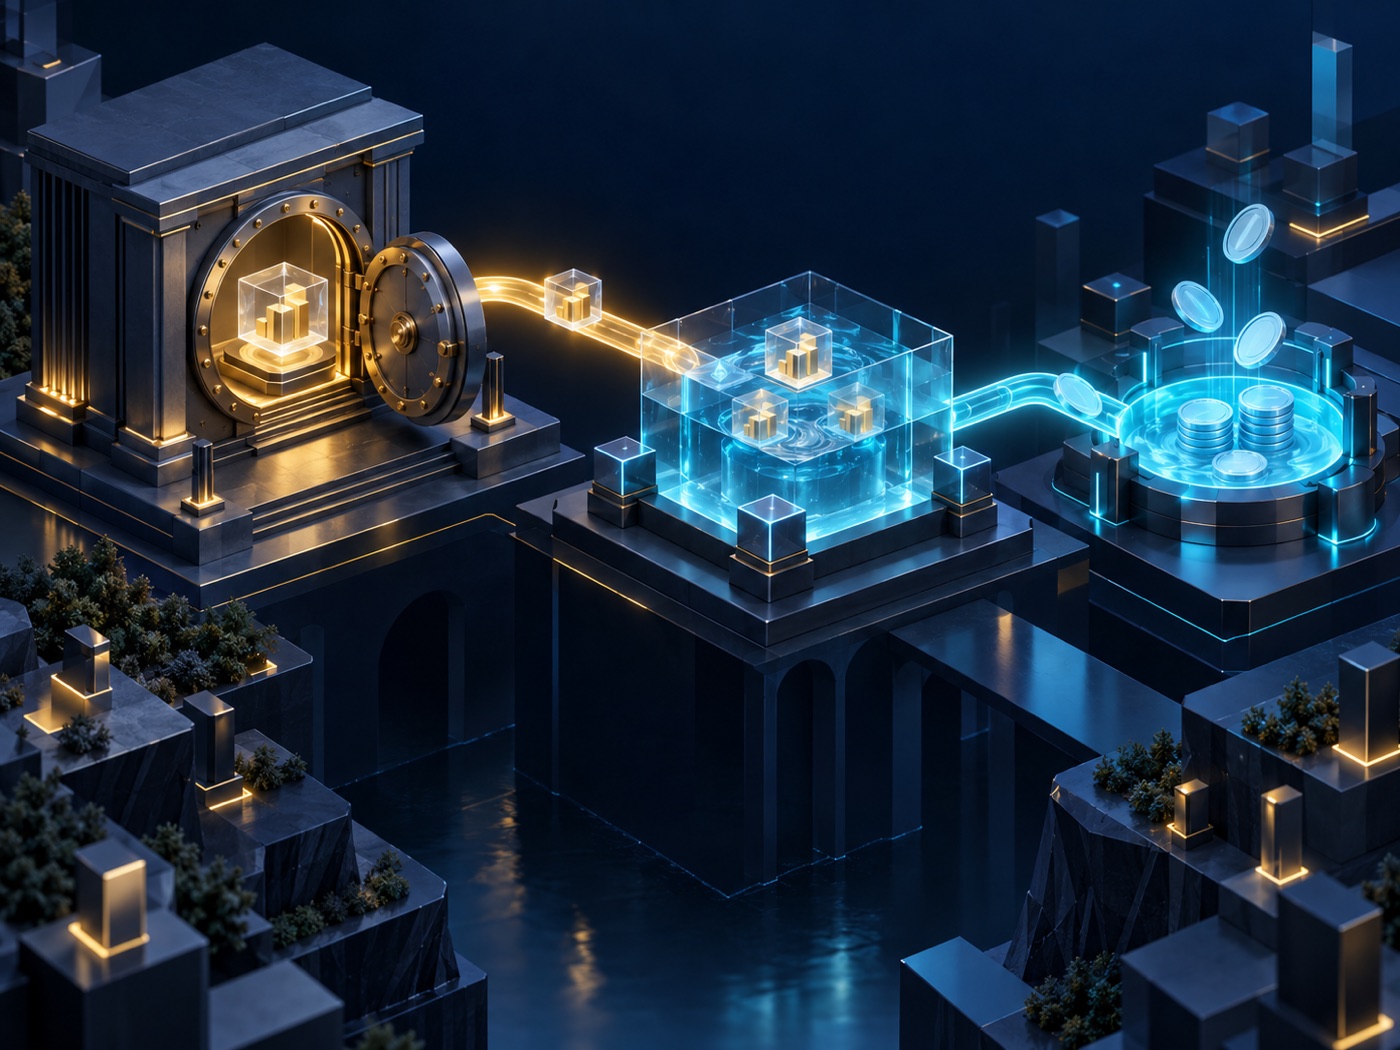
The asset path now spans issuance, collateral and settlement
A tokenized stock route begins with a specific representation. The user needs the chain, contract address, decimals, issuer context and eligibility conditions before a quote can describe the asset correctly. The symbol alone cannot identify the route input.
The next leg is a collateral decision. On Aave V4, the equities are deposited into a dedicated Equities Hub and used to borrow USDC. The market structure pools the listed names while preserving per-asset collateral factors. A user may hold a stock token in a wallet, post it as collateral, and receive a stablecoin position that carries its own health and liquidation conditions.
That sequence gives a cross-chain product a wider job. A user may hold USDC on one network, acquire a supported stock representation on another, and then move into a lending venue. The execution path needs to preserve the difference between an issuer token, a wrapped representation and a venue-specific receipt. Each form has its own liquidity and risk surface.
Market-hour state belongs in the quote
Aave's launch documentation describes a 24/7 market for supply, borrow, repay and withdraw activity. The tokenized-equity feeds publish on a 24/5 schedule, then hold the last published value over weekends and U.S. market holidays. That combination creates a meaningful execution state: the lending venue remains available while the reference market is closed.
A route ranking that shows only price and gas leaves out information that can change a position's behavior. It should also show the feed timestamp, whether the reference market is open, the last update window and the conditions that can pause a reserve during a corporate action. The user can then distinguish a fresh quote from a price held through a market closure.
The weekend activity highlighted in the recent X discussion makes this practical. Users can adjust collateral positions while the underlying market is closed, while their reference price waits for the next feed update. A route interface should attach that timing context to the amount, slippage and estimated completion time.
Cross-chain movement adds an asset-identity decision
Tokenized equity liquidity can begin on one chain while the user's funding balance sits elsewhere. Moving between those locations can involve a bridge, a message relay, a wrapped asset or a second issuance path. The route should name the representation at every transition.
A clear execution record includes the source chain and contract, the destination chain and contract, the venue used for each swap, and the transfer identifier that links the two legs. It should also distinguish a direct venue hop from a bridge-mediated asset change. This lets the user see whether the destination position is the expected token and whether the route depends on a separate liquidity pool.
The same discipline applies to stablecoins used to fund the position. USDC on a source chain, a bridged USDC form and a venue-specific deposit asset can share a ticker while carrying different transfer and liquidity conditions. A router that preserves identity can explain the path before the user signs.
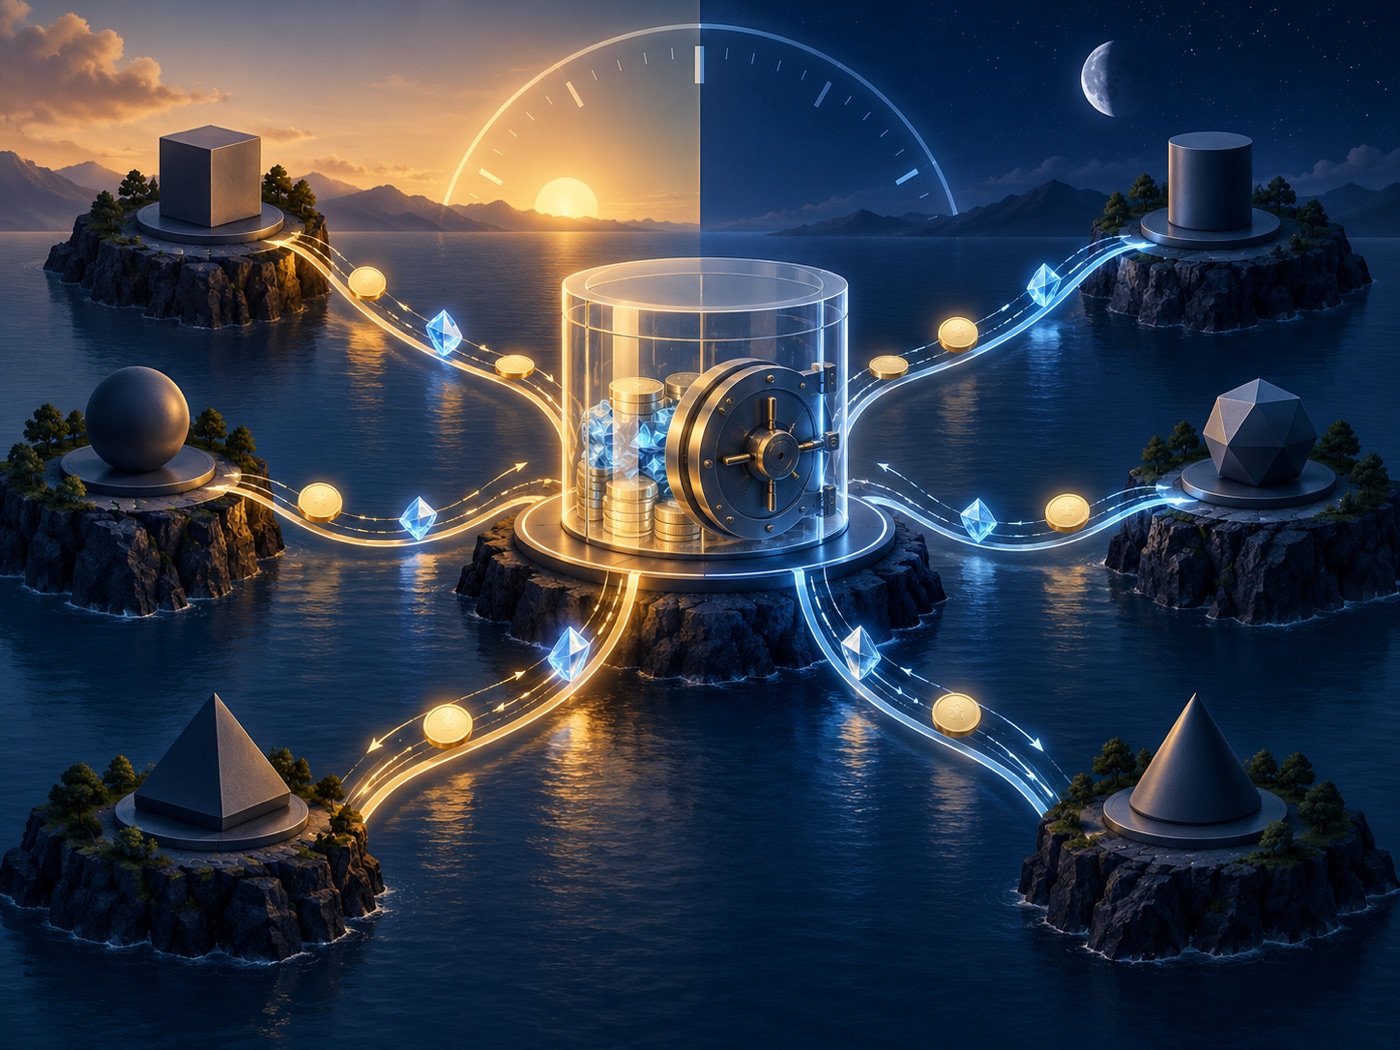
Collateral and liquidity constraints should shape route ranking
Aave's public parameters put risk conditions next to the asset list. The initial market uses collateral factors for each token, supply caps can be revisited as depth grows, and the equities are collateral-only at launch. Those conditions define how useful a route is after the swap completes.
A low-cost path can still be a poor choice when the destination reserve has limited capacity, a smaller sellable depth curve or a different collateral factor. Route comparison should therefore expose expected price impact, available depth, supply and borrow caps where relevant, and the position state created at the destination.
This is also a support advantage. If a user sees a route with its contract identities, feed timestamp, venue depth and destination conditions, a delayed or constrained position has a traceable cause. Support teams can work from evidence instead of reconstructing the path from a single transaction hash.
The OneSwap angle
The tokenized-stock activity on Base shows how quickly an asset can gain a second life inside DeFi. As tokenized securities reach lending markets, users will ask for routes that connect funding assets, supported representations and final positions across networks.
OneSwap can make that intent legible by carrying asset identity, market-hour state, venue liquidity, transfer dependencies and destination conditions through the quote. The result is a route that explains what the user will receive, which systems it relies on and where execution evidence will appear.
Tokenized assets become easier to use when the route keeps context from the first balance to the final position. Explore cross-chain execution with OneSwap at https://oneswap.ai.