Tokenized Stocks Enter DeFi: Why Route Quality Matters Next
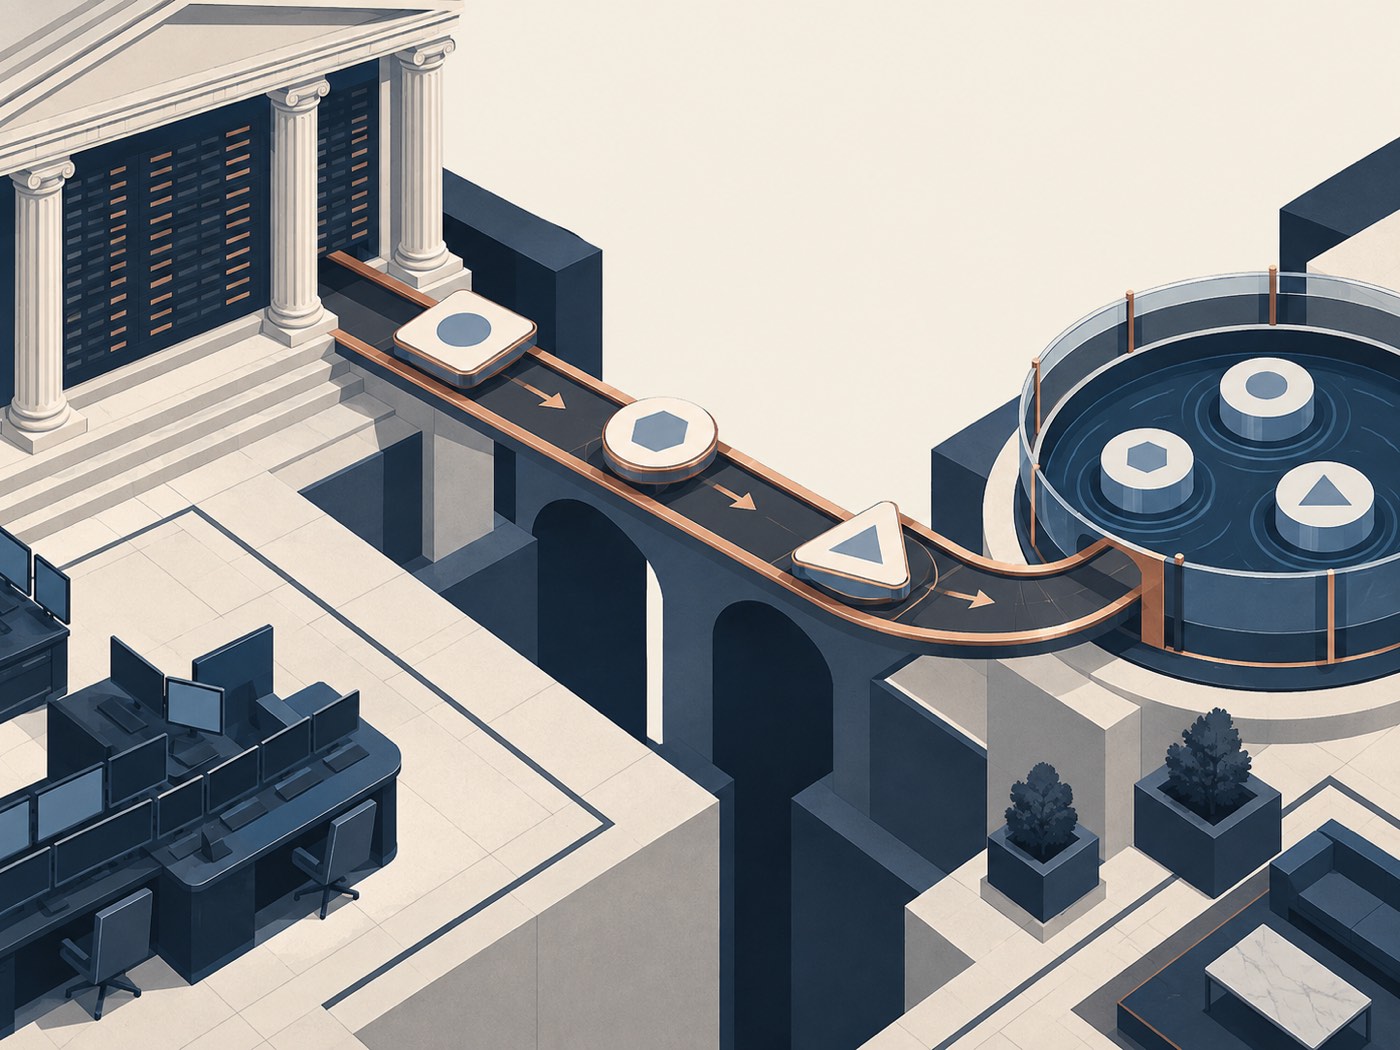
Tokenized stocks are moving toward a market structure where issuance, liquidity, execution, and settlement share the same public rails.
The policy window opens a new market surface
On September 17, the U.S. Securities and Exchange Commission issued an order granting temporary, conditional exemptive relief to Tokenized Securities Venues. The order covers trading in tokenized National Market System stocks through permissioned automated market makers and liquidity pools. The SEC announcement presents the Innovation Exemption as a route for onchain venues to test market infrastructure while the Commission gathers public comments.
The order changes the practical design question for tokenized assets. A token can represent a share, yet users still need a venue, a market maker, an eligible wallet, a price, and a settlement path. Every part of that path affects the result a trader sees.
The SEC's statement on the exemption connects tokenization with issuance, trading, transfer, settlement, and ownership records. Those functions create a full market workflow. The token is one component inside that workflow.
X is showing the conversation move from issuance to liquidity
The live X conversation over the past 48 hours adds a market signal. Token Terminal's X post reported that Uniswap led tokenized-stock DeFi TVL growth over the previous 30 days, with deposits in V4 up $54.7 million and V3 up $28.1 million, for $82.8 million combined. The post described tokenized stocks as expanding into active DeFi use.
The response from @0xbrunes framed Uniswap as a home for tokenized-stock markets and pointed to stock pairs plus V4 hooks. The post had 492 views when it appeared in the latest search results. A separate RWA marketplace signal described Prism as a live non-custodial marketplace and DEX for tokenized real-world assets from multiple issuers.
Together, these signals place attention on market plumbing. Traders can discover a token quickly. They still need a route that explains where liquidity sits, which asset is being exchanged, what constraints apply, and how the final position is recorded.
A tokenized share creates a multi-leg swap
A tokenized-stock trade can look like a simple pair on a user interface. The underlying path can include several distinct checks:
- The asset contract identifies the issuer, share class, chain, decimals, transfer rules, and corporate-action treatment.
- The wallet and account satisfy the venue's eligibility requirements for that asset and market.
- The route selects a pool, market maker, or auction with enough depth for the requested size.
- The quote includes spread, protocol fee, network fee, price impact, and any conversion between stablecoins.
- The settlement leg delivers the correct token to the intended destination and records the transaction hash.
- The final position remains traceable across the trading venue, custody layer, and portfolio ledger.
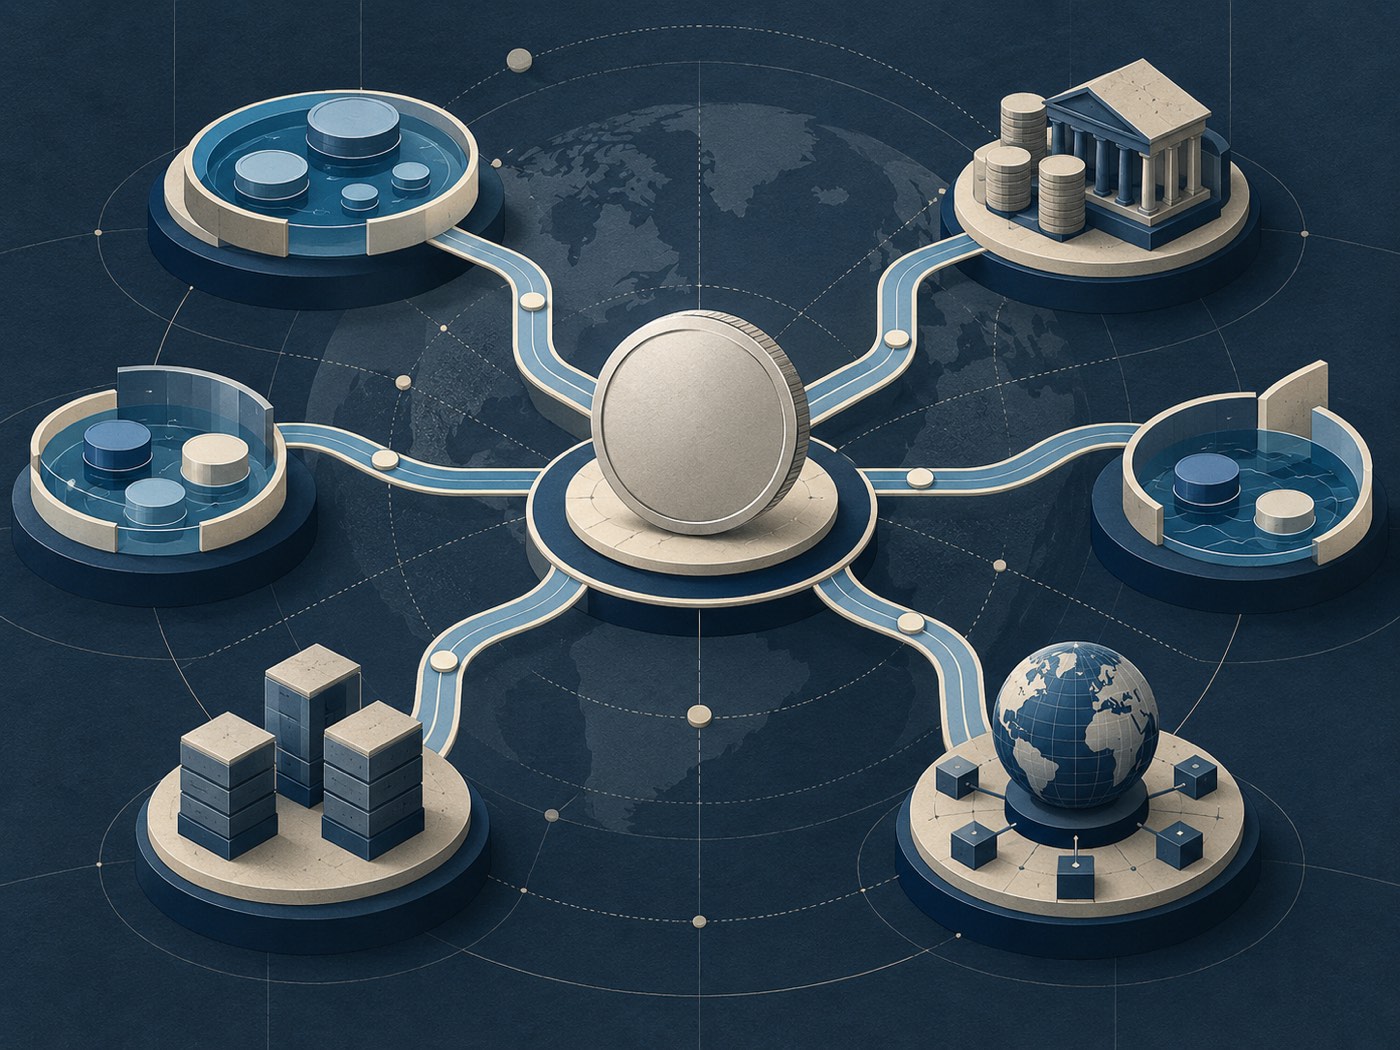
These steps create a route graph. The best path depends on asset identity, venue rules, inventory, depth, execution time, and evidence. A price screen that hides those inputs gives users an incomplete picture of the transaction.
Three route layers deserve separate inspection
Asset identity and eligibility
The first layer answers what the token represents and who can hold it. Tokenized securities can use different issuer models, transfer controls, jurisdictions, and settlement conventions. A routing engine should carry those attributes with the asset instead of treating every token as an interchangeable ERC-20.
The SEC order describes permissioned venues and liquidity pools. That detail makes eligibility part of the route decision. A path can have attractive liquidity and still fail when the receiving wallet, region, or account status does not match the venue rules.
Liquidity and execution
The second layer measures whether the route can fill the requested trade. Token Terminal's X signal gives a useful category view of deposits across Uniswap versions. A trader needs more granular evidence: pool depth at the trade size, current spread, expected price impact, hook behavior, fee tier, and the time required to complete each step.
This is where cross-chain routing becomes important. A tokenized asset may have meaningful activity on one network while the trader holds a stablecoin on another. The route then needs an eligible bridge or canonical transfer path, enough destination liquidity, and a clear failure state when a dependency pauses.
Settlement and evidence
The third layer connects the swap to a completed position. It includes confirmation depth, final token balance, venue receipt, custody record, and any follow-on update required by a portfolio or treasury system.
Settlement evidence also improves recovery. If a bridge completes after the swap, the operator can distinguish a pending route from a failed execution. If an asset transfer is restricted, the system can show the exact eligibility check that stopped the path.
DeFi growth raises the standard for route visibility
More liquidity can improve execution, yet the headline number alone cannot describe the user experience. A route-aware market should expose the conditions around the liquidity:
- Asset identity, issuer, chain, and transfer policy
- Venue, pool, market maker, or hook used for execution
- Available depth, spread, price impact, and all-in fee
- Stablecoin conversion and bridge dependencies
- Eligibility checks and destination-wallet status
- Confirmation state, final balance, and recovery instructions
This record gives traders and operators the same path view. It also creates a consistent basis for comparing routes across venues and chains.
How to evaluate a tokenized-stock route
A useful evaluation can start with five questions:
Can the route identify the asset precisely?
Check the issuer, contract, share class, chain, decimals, and transfer restrictions. Match the token to the venue's supported asset list before comparing prices.
Can the route fill the requested size?
Compare pool depth and expected impact at the actual order size. Record the quote timestamp and the liquidity source that produced it.
Can the route cross networks cleanly?
Map the origin balance, bridge or canonical transfer, destination balance, and network fee. Treat completion time as part of the route outcome.
Can the recipient hold the result?
Run eligibility and destination checks before execution. A successful swap requires a deliverable final position.
Can the operator prove completion?
Keep the quote, transaction hash, bridge receipt, final balance, and venue status together. This evidence turns a trade into a reviewable process.
OneSwap puts route context beside the swap
Tokenized stocks are entering DeFi through venues that connect regulated market rules with programmable liquidity. That combination creates a larger route graph for traders, operators, and builders to inspect.
OneSwap can put the asset, chain, venue, fees, and settlement path beside the rate so users can compare the full route. Explore cross-chain swaps at OneSwap.
Originally published at https://oneswap.ai on September 19, 2026.